Ethiopia’s Investment Incentives Directive No. 1064/2025: Legal Guidance from a Business Law Firm in Addis Ababa
Introduction
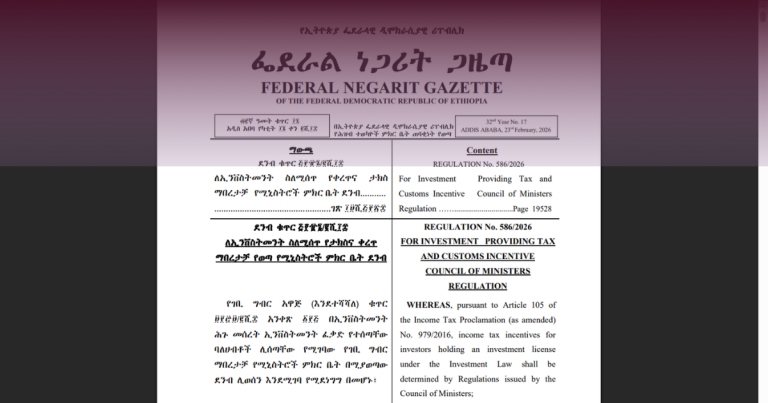
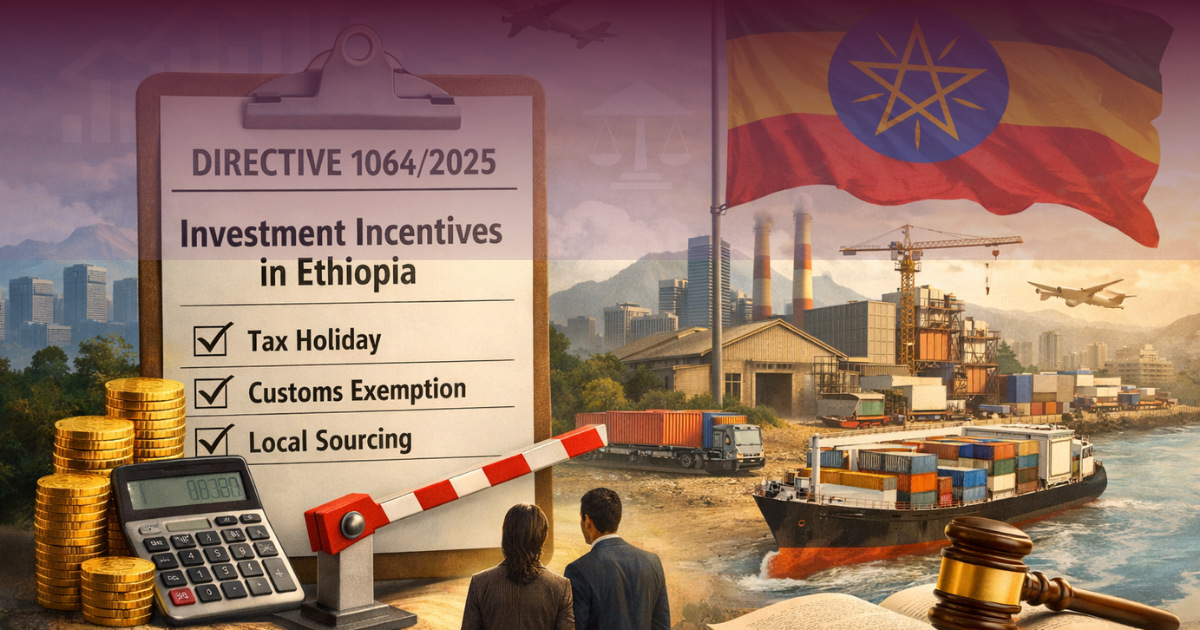
In Ethiopia, investment incentives are essential for attracting both domestic and foreign investors, as they directly influence business decisions and promote economic growth. In this context, the Ministry of Finance issued Directive No. 1064/2025 to regulate the implementation of investment incentives and ensure accountability, transparency, and compliance.
While Ethiopia’s Investment Proclamation and Investment Incentives Regulation provide investment incentives, the Directive actively determines how investors access, monitor, and comply with these benefits in practice. For investors and businesses, guidance from a business law firm in Addis Ababa is essential to navigate this regulatory layer effectively.
The Directive specifically regulates
The Ministry of Finance issued Directive No. 1064/2025 to address practical gaps in implementing Ethiopia’s investment incentives regime. Unlike the Investment Incentives Regulation, which defines the scope of incentives, the Directive regulates their administration and enforcement.
Specifically, the Directive governs:
- the procedure for granting income tax holidays
- the documentation required to activate investment incentives
- monitoring and reporting obligations during the exemption period
- the grounds and legal process for revoking incentives
- the administration of customs duty exemptions
- coordination between investment authorities, tax authorities, and customs bodies
Through these mechanisms, the Directive transforms investment incentives from policy promises into conditional, enforceable legal privileges. This distinction proves critical, yet investors frequently overlook it when they do not seek advice from an experienced investment law firm in Ethiopia.
Legal Basis and Regulatory Framework
The Ministry of Finance issues Directive No. 1064/2025 pursuant to the Investment Incentives Regulation No. 517/2022 (as amended) and the Investment Proclamation. Legally, the Directive does not create new incentives; instead, it operationalizes existing incentives by defining procedures, controls, and consequences.
A corporate and investment law firm in Addis Ababa typically advises investors by interpreting the Directive together with:
- the Investment Proclamation
- the Investment Incentives Regulation
- sector-specific investment instruments
Investors must review both the Directive and the Regulation together, as they cannot lawfully claim incentives based solely on the Regulation.
Income Tax Holiday: Conditions and Legal Compliance
Eligibility Criteria
Under the Directive, an investor may qualify for an income tax holiday only if the investor:
- operates in an incentive-eligible sector
- holds a valid investment and business license
- obtains official confirmation from the competent investment authority
For investment expansion or upgrading projects, additional regulatory requirements apply. Determining eligibility often requires review by an investment advisory law firm in Addis Ababa, particularly where multiple incentives are involved.
Compliance Obligations During the Exemption Period
The Directive expressly clarifies that tax exemption does not suspend compliance obligations. Investors must:
- submit financial statements within statutory deadlines
- declare income in accordance with tax administration laws
Failure to comply may result in penalties and eventual revocation of incentives. Continuous compliance oversight by a commercial law firm in Ethiopia significantly reduces this risk.
Force Majeure Protection
Where non-compliance results from force majeure events such as war, natural disasters, or man-made emergencies, the Directive allows relief from penalties and interest, subject to verification by the relevant investment authority. Proper documentation and legal substantiation are essential.
Revocation of Investment Incentives
Grounds for Cancellation
The Directive empowers authorities to revoke incentives where:
- incentives were obtained through false or misleading information
- the licensed investment activity is discontinued
- reporting and regulatory obligations are not fulfilled
This confirms that investment incentives are conditional benefits, not vested rights.
Right to Be Heard and Appeal
Before revocation, the Directive guarantees due process, including:
- prior written notification
- a 10-day period to submit explanations
- issuance of a reasoned decision
An appeal may be lodged within 30 days. At this stage, representation by a law firm in Addis Ababa specializing in investment and administrative disputes is strongly advised.
Customs Duty and Import Incentives
The Directive regulates duty-free importation of:
- capital goods
- construction materials
- spare parts
It introduces phased utilization, post-clearance audits, and guarantees for excess imports. Legal review by a business law firm in Ethiopia helps align import plans with customs and investment compliance requirements.
Domestic Purchase Requirement
Where capital goods or construction materials are available locally at reasonable price and quality, investors are required to purchase domestically. In such cases, refund mechanisms apply for taxes paid on production inputs. Misinterpretation of this rule is a common compliance risk.
Sector-Specific Clarifications
The Directive provides interpretative guidance for specific sectors, including:
- Special Economic Zones
- metal and construction industries
- agro-processing and grain milling
- technical and vocational training services
These clarifications are particularly relevant for foreign investors seeking advice from a corporate law firm in Addis Ababa.
Practical Implications for Investors
Directive No. 1064/2025 reflects a regulatory shift toward:
- enhanced monitoring
- stronger enforcement
- inter-agency coordination
Investment incentives in Ethiopia now operate within a compliance-driven framework, requiring proactive legal planning supported by a trusted business law firm in Addis Ababa.
Conclusion
Ethiopia’s Investment Incentives Directive No. 1064/2025 confirms that incentives are earned through compliance, transparency, and regulatory alignment. While the Investment Incentives Regulation defines available benefits, the Directive determines whether those benefits are retained or lost.
Engaging an experienced investment and commercial law firm in Addis Ababa ensures that incentives are lawfully obtained, properly maintained, and protected from cancellation risk.