Analysing the National Bank of Ethiopia’s Latest FX Reforms
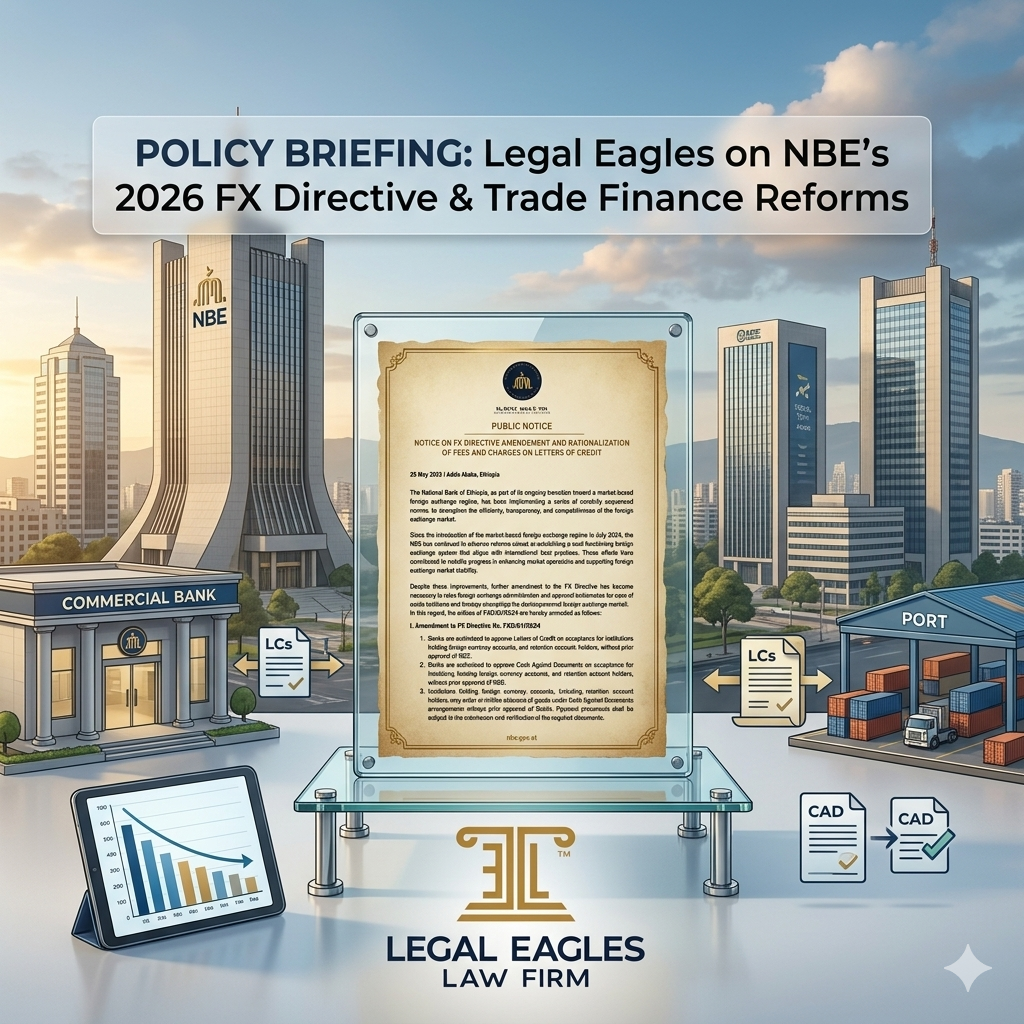
The National Bank of Ethiopia (NBE) wants a market-based foreign exchange regime. To accelerate this transition, the NBE amended its landmark FX Directive. This policy shift introduces a sweeping rationalization of Letter of Credit (LC) fees. These changes will dismantle long-standing bureaucratic bottlenecks. They will lower transaction costs for traders. This update aligns Ethiopia’s trade finance ecosystem with international standards.
The NBE introduced a sweeping foreign exchange market liberalization in July 2024. Since then, the central bank has pursued sequential reforms. These steps enhance market transparency. They also protect market stability. This latest update targets operational inefficiencies, handing unprecedented autonomy to commercial banks and trusted market actors to expedite global trade.
Decentralizing Approvals: A Boost for Cross-Border Logistics
The core of the newly announced amendment is the deliberate removal of central bank oversight for routine trade financing instruments. Previously, international trade required tedious, multi-layered clearance processes. These delayed workflows often left shipments stranded at ports. Consequently, the bottlenecks drove up capital costs for businesses.
The NBE has fundamentally restructured this workflow across three key pillars for institutions holding foreign currency accounts and retention accounts:
- Autonomy over Letters of Credit (LCs): The NBE now grants commercial banks full approval authority. Banks can approve Letters of Credit on acceptance independently. This removes prior central bank clearance completely.
- Direct Processing of Cash Against Documents (CAD): The NBE removed the requirement for prior central bank intervention. Consequently, commercial banks can greenlight CAD transactions autonomously.
- Logistical Freedom to Initiate Shipments: This rule marks a major victory for supply chain predictability. Qualifying institutions can now order goods under CAD arrangements. They can initiate shipments before obtaining bank approval. Banks still verify standard documents upon arrival before processing payments, but the new rule completely clears the initial logistical bottleneck.
The NBE is shifting to a market-based framework. This replaces the old environment of rigid pre-approval. The new post-shipment verification cuts down import timelines. It heavily boosts the agility of Ethiopian exporters.
Rationalizing LC Fees: Ending Inconsistent Pricing
Beyond administrative relief, the NBE is taking aim at the cost of trade finance itself. Historically, commercial banks applied fragmented, flat-rate, or front-loaded fees on LC transactions. These pricing mechanisms frequently deviated from global norms and disproportionately penalized short-term trade arrangements.
To enforce international pricing discipline, the NBE has instituted a mandatory two-pronged framework for commercial banks:
Annualized, Pro-Rata Pricing
Banks must now calculate fees and charges on LC transactions on an annualized basis and apply them pro-rata according to the exact tenor (duration) of the credit line. If an importer utilizes an LC for only 90 days, the bank bills them only for that specific portion of the year. This prevents institutions from charging blanket annual fees for short-term financing.
Strict Fee Capping
To shield businesses from predatory pricing, the NBE reiterated that these annualized fee rates must not exceed the maximum limits previously dictated by the central bank.
Strategic Implications: Incentivizing the Formal Economy
The NBE’s decision to limit these sweeping relaxations specifically to foreign currency and retention account holders is highly strategic. By reserving these operational and financial benefits for businesses that generate and maintain hard currency within the domestic banking sector, the central bank is creating a powerful incentive for exporters and international enterprises to formalize their FX flows.
The shift marks a profound transition for Ethiopia’s economy. Under the old regulatory environment, traders faced centralized NBE approval delays for LC and CAD acceptance, alongside inconsistent trade finance fees across commercial banks. The new framework swaps this out for decentralized approvals delegated entirely to commercial banks, immediate shipment initiations that optimize logistics, and standardized, predictable, pro-rata pricing aligned with global standards.
Moving Forward
The NBE’s latest directive represents more than just a regulatory clean-up; it introduces a structural upgrade that reduces the cost of doing business in Ethiopia. By converting the banking sector from a regulatory gatekeeper into an agile trade facilitator, Ethiopia is signaling to the global market that its economic liberalization remains firmly on track.
As the central bank continues to monitor market developments, the onus now shifts to commercial banks to rapidly adapt their internal compliance systems to support a faster, cheaper, and more efficient trade environment.