Real Estate Investment Funds Ethiopia: Draft Guide
The Ethiopian Capital Market Authority (ECMA) is actively advancing its draft Collective Investment Schemes (CIS) Directive. The draft framework is still under legislative review. However, it introduces groundbreaking mechanisms to formalize, scale, and diversify economic participation.
The draft outlines five distinct fund categories. Among them, Real Estate Investment Funds (REITs) represent a fundamental shift for all property market players.
The Shift from Direct Acquisition to Pooled Liquidity
Historically, direct, capital-intensive asset acquisitions and informal, uncoordinated individual investing have characterized Ethiopian real estate.
The draft directive establishes a structured, highly regulated environment for property-backed pooled vehicles. By allowing investors to pool smaller contributions into a single corporate entity, the framework transforms real estate. It turns a highly illiquid asset class into a transparent capital market instrument.
What Makes the Real Estate Fund Framework Uniquely Interesting?
The draft directive avoids copying general equity fund rules. Instead, it establishes specialized parameters tailored to the unique realities of property development. Several key features make this framework particularly notable:
- High-Leverage Flexibility: Generally, the draft directive caps standard mutual fund leverage at 20% of the portfolio value. However, property development is naturally capital-intensive. Therefore, the draft exceptions permit real estate funds to borrow up to 40%. This allows fund managers to utilize debt strategically to secure high-value commercial properties.
- The Focus on Pure Income Generation (The 80% Rule):Under the draft rules, a real estate fund must invest at least 80% of its Net Asset Value into income-generating assets. This prevents fund sponsors from using a real estate wrapper to run a highly speculative asset trading or land-flipping business. This forces the fund to function as a yield-producing engine, like commercial rentals. Consequently, it protects investors by aligning the fund with predictable, long-term returns.
- The “Trigger Threshold” for Stricter Compliance (The 20% Rule): General schemes holding or intending to hold over 20% of their Net Asset Value in real estate must follow specialized rules. This acts as a clear regulatory boundary. It prevents general funds from quietly slipping property onto their balance sheets. It also triggers heightened competence and management requirements.
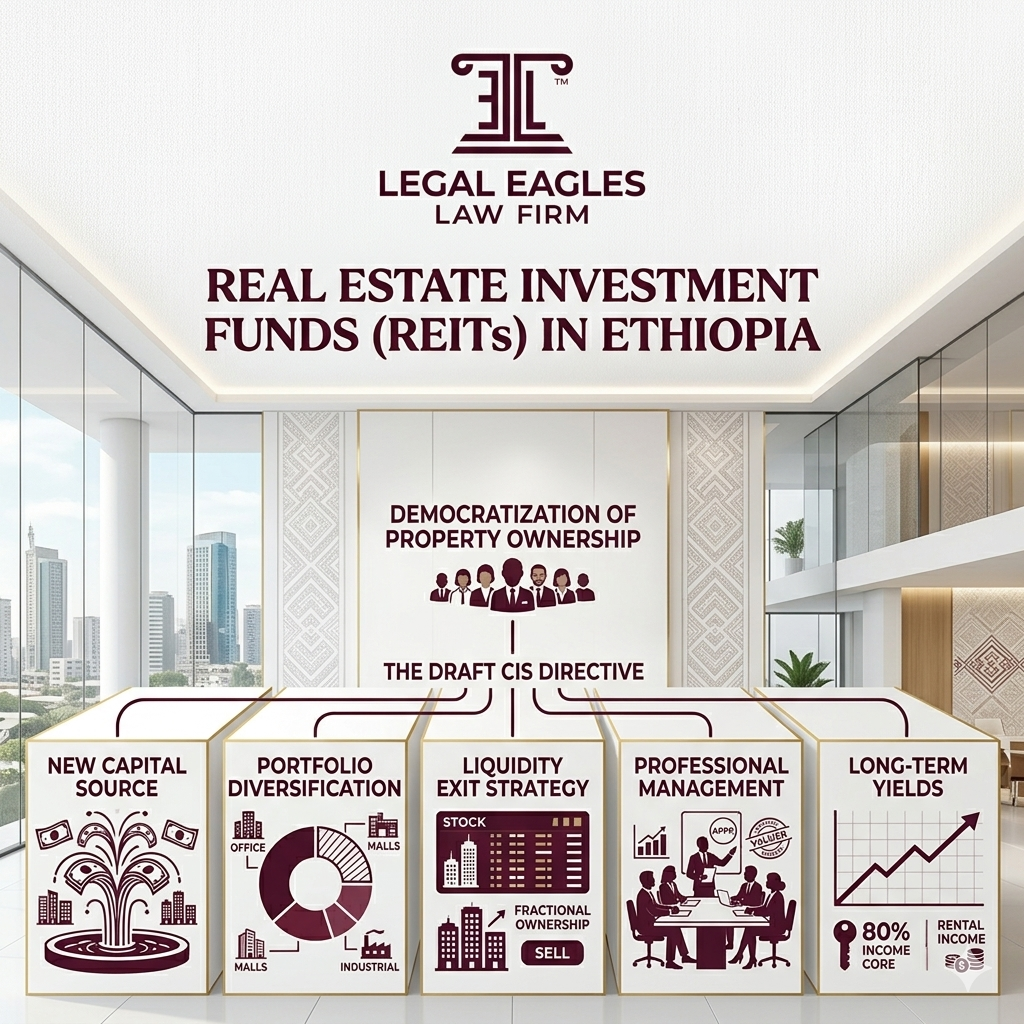
- Property Democratization: Investors can pool individual contributions into a single corporate vehicle. This allows retail investors to own fractions of large property developments. This removes the burden of buying, financing, or managing physical buildings directly.
What Does This Move Mean for Real Estate Investors?
For Ethiopian real estate investors, this draft regime fundamentally changes how developers conduct, finance, and scale property businesses.
- Exiting the “Liquidity Trap”: Real estate has always been highly illiquid. If an investor owns a commercial building in Addis Ababa and needs cash, they cannot easily sell 5% of that building overnight to raise capital. By structuring real estate into a fund, sponsors convert property assets into divisible, liquid shares or units. Capital markets let investors trade fractional fund shares easily. This provides a viable exit strategy and fast cash without selling physical buildings.
- Traditional property funding relied on massive equity, pre-sales, or high-interest bank loans. Now, developers can establish a fund to source capital directly from retail savers, institutional investors, and pension funds.This opens up an entirely new, non-banking liquidity tap to finance major commercial or residential projects.
- Lowering the Entry Barrier for Portfolio Diversification: To diversify a real estate footprint across commercial offices, retail malls, and industrial warehouses, an investor historically needed massive liquid capital to buy each asset class directly. Investors can now diversify their risk by putting smaller amounts of capital into a single real estate fund that already holds a balanced mix of premium, cash-flowing assets.
- Hands-Off Professional Management: Being a traditional landlord means dealing directly with construction delays, municipal permits, tenant disputes, rent collection, and physical property maintenance. Investing through a fund shifts the property owner into a passive investor role. The draft directive’s mandate for Professional Property Managers, Independent Appraisers, and Licensed Custodians means qualified, licensed specialists handle day-to-day operations and safeguard legal titles, ensuring institutional transparency.
- Transitioning from Speculative Flipping to Long-Term Yields: A large portion of informal real estate investment relies on buying undeveloped land, holding it, and flipping it for speculative capital gains. Because the draft framework enforces an 80% income-generating rule, the regulatory environment actively favors projects that build, lease, and generate consistent rental yields.
Institutionalizing the Ecosystem
Beyond asset allocation, the draft directive introduces mandatory layers of governance designed to eliminate the risks of informal property financing. Once finalized, fund sponsors will not manage real estate investment funds in isolation. The integration of independent, licensed capital market service providers including property managers, independent appraisers for verifiable Net Asset Value calculations, and licensed custodians will establish institutional transparency and accountability that helps protect investor capital.
Furthermore, in alignment with the Commercial Code of Ethiopia, sponsors looking to establish or operate a real estate scheme must structure the fund as a recognized corporate form specifically a Share Company, Private Limited Company (PLC), or Limited Partnership.
Legal Readiness and Corporate Strategy
Because this directive remains in the draft and pre-enactment stage, commercial property developers, asset managers, and corporate boards have a vital window to structure their corporate governance and investment vehicles ahead of active law enforcement.