Ethiopia Tax Debt Priority: Why the Taxman Beats the Bank
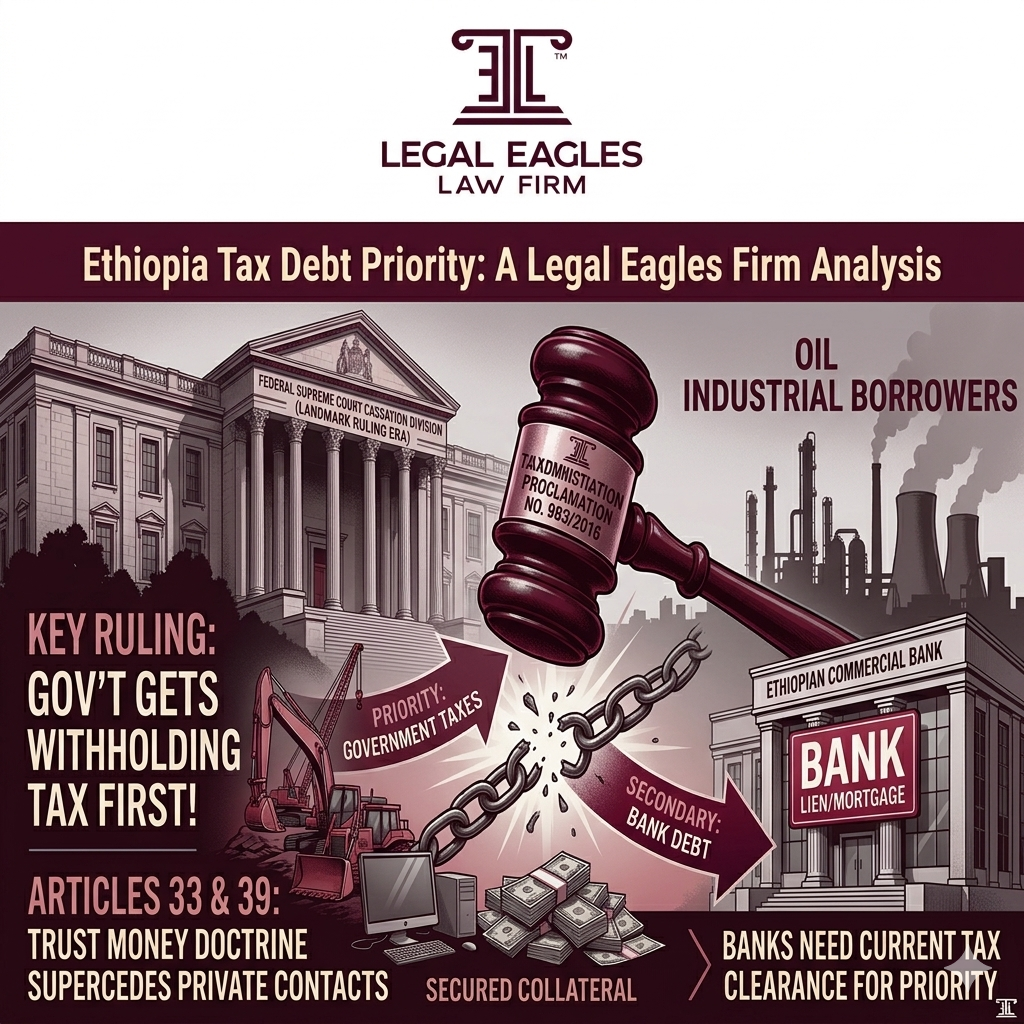
In the world of corporate finance, “Security” is traditionally king. When a business defaults, a bank holding a registered mortgage or lien typically claims first priority for payment. However, in Ethiopia, the Tax Administration Proclamation No. 983/2016 contains powerful “super-priority” provisions that can retroactively strip a bank of its status.
When the tax authority and a commercial bank both claim the same asset, the law often acts as the referee who hands the trophy to the taxman. Here is the breakdown of the legal mechanics at play.
1. The “Trust Money” Doctrine (Article 33)
The first hurdle for any secured creditor is the classification of debt. The law treats some taxes differently than standard liabilities. Under Article 33, the state defines Withholding Tax and VAT as “Trust Moneys” because taxpayers collect them on the government’s behalf.
- The Legal Charge: Article 33 establishes that any tax unpaid by a taxpayer is a charge (a legal lien) upon the property of that person.
- The Hierarchy: Since you serve as a “trustee” for government funds, the law regards the state’s claim to recover those funds as absolute. Courts frequently rule that this “State Trust” overrides any private contractual mortgage, placing the government at the very top of the payment waterfall.
2. The Power to Seize: Article 39
If a taxpayer fails to pay, the Tax Authority does not need to wait for a bank to foreclose. Article 39 grants the Authority broad power to seize a taxpayer’s property to satisfy unpaid tax debts.
- Scope of Seizure: This power applies to any tangible or intangible property, including business equipment, vehicles, and real estate.
- The Leapfrog Effect: Even when a bank holds an asset as collateral, the Authority uses Article 39 to assert physical control over that property. This effectively halts a bank’s own foreclosure process, as the government takes “custody of the law” over the property.
3. Who Sells the Asset? (Article 41)
The most critical question for lenders and business owners is: Who holds the hammer at the auction? Article 41 provides the definitive answer.
- The Mandate to Sell: Article 41(1) explicitly grants the Tax Authority the right to sell seized property.
- The Auction Process: Under Article 41(2), the Authority can proceed with a public auction typically 10 days after the seizure.
- Distribution of Proceeds: This process tests the bank’s priority. Once the Authority sells the asset, it applies the proceeds to the tax debt first. The bank receives the remaining balance only after the Authority recovers all “trust money” and general tax charges.
The “Clearance Rule”: A Warning for 2026
To protect themselves, banks are increasingly relying on a “Clearance Defense.” To maintain priority, a lender must produce a written Tax Clearance Certificate from the exact moment they created the security. If the borrower owed tax debts when they signed the mortgage, the state ranks the bank’s interest as secondary under Article 33.
Strategic Advice: Protecting Your Assets
As a legal partner, our advice for the 2026 fiscal year is clear: Tax compliance is no longer just a regulatory hurdle; it is the only way to protect your collateral.
- Banks: Conduct frequent tax audits of your borrowers. A mortgage is only as strong as your client’s last tax clearance.
- Businesses: If facing a cash crunch, always prioritize “Trust Taxes” (VAT/Withholding). Defaulting on a bank loan leads to negotiation; defaulting on these taxes leads to an Article 41 auction.